Turners’ profit defies oil shock
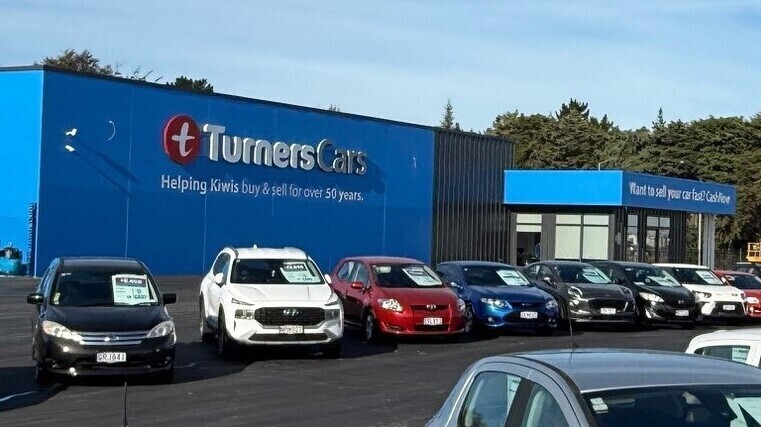
Turners Automotive Group has announced a record result for the six months ended September 30, with net profit before tax (NPBT) of $31.5 million in the first half of the 2027 financial year.
The figure is up four per cent from the same period last year, when it was $30.4m, and extends an unbroken run of record half-year and full-year results since the end of March 2021.
The group’s latest half-year delivered strong growth in finance, with NPBT rising 24 per cent on a loan book up 26 per cent, which more than offset lower vehicle margins in auto retail following the worst oil price shock since the 1970s.
Turners says it has minimised short-term downside risk in auto retail in response to the impact of rising fuel prices, while continuing to invest in the 2031 financial year growth plan.
Other key financial highlights announced on November 20 include revenue of $225.3m and earnings before interest and taxes of $35.3m, both up three per cent from a year ago, and net profit after tax growing four per cent to $22.6m.
Earnings per share increased by two per cent to 24.8 cents and a fully imputed dividend of 8c per share was declared for the second quarter.
An announcement to the NZX notes the half-year was shaped by the oil price shock that followed the onset of the Iran-US conflict in late February.
Demand and pricing for larger and diesel vehicles fell, and vehicle margins, which had been building through the previous six months, fell from April and hit a low point mid-year.
Turners says it responded with the playbook used through the 2024 and 2025 financial years, which included more selective buying weighted toward the sub-$15,000 segment, pricing to maintain stock turn, cost discipline, higher interest rate hedging and a retained provisioning overlay in finance.
With stock purchased before the shock now largely sold, vehicle margins have recovered from their mid-year low and are running above the first-half average, although they remain below pre-shock levels.
Todd Hunter, group chief executive, adds: “We have shown over the last five years that this business is diversified and resilient in a recession, but it is not immune to an oil shock, which arrived suddenly and hit vehicle margins within weeks.
“However, finance has had its best half yet, growing the book 26 per cent while arrears fell and credit quality improved, and that growth offset the margin pressure in auto retail.
“In auto retail we moved quickly: we tightened buying, shifted stock to the cheaper end of the market, held costs and protected the balance sheet. Volumes held up. Margins took the hit but are now recovering, albeit slowly.”
Half-year 2027 results by segment. Figures compared with same period of 2026.
Auto retail
Revenue $151.3m, down one per cent; NPBT $14.2m, down 11 per cent
Vehicle margins were lower than the first half of the 2026 financial year, driven by the devaluation of larger vehicles purchased before the oil shock and the lower dollar margin per unit of the sub-$15,000 strategy.
Higher discounting than anticipated was required to clear pre-shock stock. Sourcing was also restricted but purchases rose year on year and owned units sold rose three per cent as stock was repositioned towards lower-priced vehicles.
Consignment volumes fell 12 per cent as lease customers extended contracts amid uncertainty. Turners says this is largely timing and should recover as confidence returns.
Damaged and end-of-life volumes were broadly stable with improving yields, while trucks and machinery revenues fell 18 per cent.
As for new branches, Whanganui and Hastings will open in December ahead of schedule, and sites have been secured in Takanini and Ormiston, East Auckland.
Finance
Revenue $44, up 19 per cent; NPBT $11.8m, up 24 per cent
A record result as the loan book grew 26 per cent to $622m, when compared with $493m at September 2025.
Third-party consumer lending increased 40 per cent and direct lending rose 23 per cent over the same period, reflecting market share gains across the originator base.
Total arrears were 2.2 per cent at September 2026, down from 2.5 per cent at March 2026, and 31-plus day secured consumer arrears of one per cent remain well below the industry average of 2.9 per cent.
Unsecured and partially secured lending is limited to Premium and Tier 1 customers, and a Premium+ category for 800-plus credit scores was introduced.
Insurance
Revenue $25.3m, up two per cent; NPBT $8.2m, down three per cent
Gross earned premium rose four per cent and net earned premium climbed four per cent to $19.7m, with growth through dealer and finance broker partnerships and digital channels.
Claims frequency and cost increased in certain areas, with mechanical breakdown insurance claims inflation concentrated in European vehicle categories, lifting the loss ratio and offsetting premium growth.
Motor vehicle insurance gross written premium dropped six per cent against the first half of 2026 because of cost-of-living pressures and heightened competition.
Turners Servicing & Repairs
Revenue continued to grow half-on-half, with this section of the group now providing pre-purchase inspections exclusively for VTNZ in covered regions.
It is also developing a small and medium business fleet and leasing opportunity, and ramping cross-sell into the wider Turners customer base.
EC Credit Control
Revenue $4.6m, no change; NPBT $1.2m, up 17 per cent
Profit rose on cost discipline and in-sourced sales. Referral volumes remained constrained by holds as several major corporate clients undertake system implementations and security audits.
Outlook
Turners explains changes since May include the oil shock lasting longer and its effect on vehicle margins being larger than expected.
Lease returns have also been lower and market prices for diesel utes and SUVs have fallen, holding back consignment volumes. Claims costs in insurance have risen in certain categories.
What has not changed is that group profit is ahead of last year, finance is growing its loan book and the strategy set out at the March 2026 Investor Day remains the same, as is the $100m NPBT target for the 2031 financial year.
Turners is targeting $65m NPBT for the 2027 financial year, which is 12 months ahead of its original medium-term forecast.
“However, we note that the second half of FY26 was a particularly strong half, as the economy started to regain momentum,” the company says.
“Large-engine and diesel vehicle sales are likely to remain challenging until Middle East tensions ease and consumer confidence recovers, with any further fuel price spikes potentially delaying recovery.
“We view the current uncertainty as a temporary issue, our four site openings and continued finance momentum are supportive to our FY28 outlook.”