Directors repeat takeover support
The independent directors of 2 Cheap Cars (2CC) have reiterated their recommendation that company shareholders accept a takeover offer before the September 30 deadline.
Michael Stiassny, chairman, outlined the details of the 90c-a-share bid from Sena & Co Ltd, which is owned by 2CC’s founder and chief executive David Sena, during the group’s annual shareholders’ meeting.
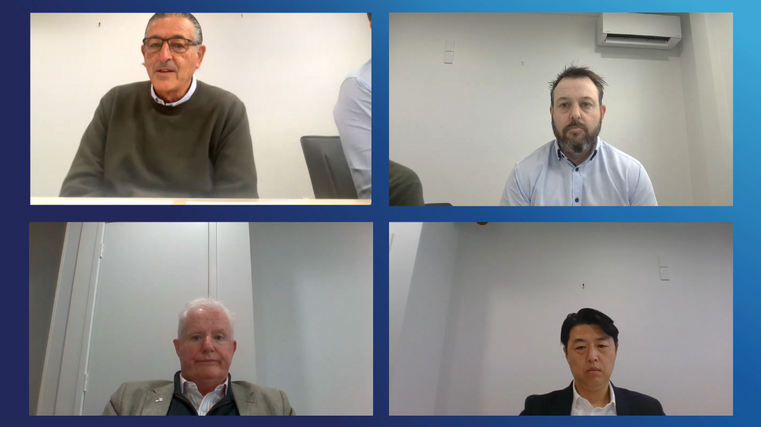
Attendees at the online meeting on September 25 were told that independent directors Stiassny and Gordon Shaw formed a committee to consider the takeover proposal after it was made on July 27.
At that time, the offer for all ordinary 2CC shares not already owned by Sena & Co was 80c and the pair recommended that shareholders accept the offer.
Their reasons included that it represented a 21 per cent premium to the pre-announcement trading price of 2CC shares, a premium to various volume-weighted average prices up to 12 months, and no competing offer had emerged.
Sena & Co later increased its offer to 90c and the level of acceptances was 12.525 per cent as at 5pm on September 22.
This means it needs a further 1.321 per cent to complete the deal, which is conditional on Sena & Co receiving acceptances that would give it, together with its existing shareholding, 90 per cent or more of 2CC’s voting rights.
Stiassny told today’s meeting: “Your independent directors continue to recommend that shareholders accept the offer for the reasons laid out in our target company statement.”
Shareholders did not raise any questions about the takeover during the meeting.
‘Credible result’
In his address to shareholders, Stiassny says 2CC has been riding “the roller coaster that is the New Zealand economy” through the 2026 financial year and into the start of the current one.
“While there have been periodic improvements to economic data, these have often been short-lived or inconsistent and any green shoots, shallow-rooted,” he explains.
“Our strategic operational priorities – namely to improve execution, strengthen sourcing, and continue to develop our retail network in a challenging market – have largely been implemented and saw the business deliver a credible result.”
Stiassny adds the results for the year to March 30, 2026 – net profit after tax (NPAT) of $3.2 million and “steady” revenue of $81.7m – demonstrate resilience.
“The improvement from a first-half NPAT of $1.01m to a full-year result exceeding our January guidance of at least $3m was indicative of just how volatile the market was and remains.
“The clean car standard remained a bone of contention, adversely impacting NPAT by approximately $1.7m relative to FY25.
“The company did what it could in an uncertain regulatory environment, adjusting our compliance model and sourcing strategies, which did provide some relief as revised settings took effect in the final quarter.
“We also made targeted investments in retail locations and buying capabilities, decisions carefully evaluated by the board for their long-term growth potential.”
He notes early trading in the 2027 financial year has been encouraging but remains variable.
“We do not expect conditions to stabilise or improve markedly in the short-term, particularly with the general election only weeks away.
“Our fundamental mission remains unchanged: to provide quality, affordable vehicles to New Zealanders while generating sustainable returns for shareholders.”
Carbon costs
Angus Guerin, chief financial officer, was next to address the shareholders’ meeting and repeated details of the annual results announced in May.
He says the first half of the 2026 financial year was affected by higher carbon costs and subdued demand, while the second half benefited from firmer margins and better trading conditions.
“That improvement allowed us to finish the year close to the previous year’s profit despite [a number of] pressures,” he says.
“Total clean car standard fees increased through the first three quarters, reaching approximately $600,000 in the third quarter, before falling to around $300,000 in the fourth as the revised settings flowed through.
“The timing is important. Profitability was already improving before carbon costs reduced, supported by better vehicle margins, procurement and finance and insurance performance. The reduction in carbon costs then provided additional support in the final quarter.
“The stronger second-half result reflects both the operational improvements we made and the benefit of easing cost pressures. While encouraging, it also highlights how sensitive our earnings remain to market conditions.”
Guerin explains that while market conditions remained mixed, factors such as falling interest rates and foreign exchange have continued to support the business.
As for the challenges, he says carbon costs materially affected profitability in the 2026 financial year and future government policy will remain important to 2CC’s purchasing decisions and earnings.
“In short, the regulatory uncertainty around implementation of the clean car standard remains one of the most significant external influences on our margins.
“As FY27 plays out, we will need to remain flexible, responding quickly to changes in purchasing costs and customer demand, while maintaining our focus on product mix, finance performance and operating efficiency.”
As for the company’s footprint, Guerin explains 2CC has continued to reshape the network around larger, more productive locations, including a new Wellington branch and securing a dedicated vehicle refurbishment hub in Christchurch.
“We have also closed underperforming branches in New Lynn, Westgate and Palmerston North. Sylvia Park is developing into a flagship location, and Henderson opened in early August ahead of the upcoming closure of our Penrose site.
“The priority now is to make better use of the network and give customers a consistent experience, including the presentation and layout of our branches.
“The company will continue to review its retail footprint having regard to market conditions, operational capacity, and expected returns.”
He notes 2CC is also improving how vehicles move through the business, from purchasing to preparation and sale, and it continues to fine-tune the balance between work completed in-house and services provided by external suppliers.
Shareholders were also told the main marketing initiative of the past year was rebuilding the company’s website and 2CC is now building the capability and brand presence around it.
“We have strengthened our in-house marketing capability and are working towards a more consistent look, tone and message across our website, advertising, social channels and branches,” adds Guerin.
“We are also working with a creative agency on a new brand campaign. We want our marketing to create familiarity with the brand as well as generate enquiries today.”
‘Better margins’
For the five months ended August 31, unaudited figures show 2CC sold 3,010 vehicles, down two per cent year-on-year, while revenue rose five per cent to $35.1m.
Gross margin improved to 25 per cent from 19 per cent, and finance penetration increased to 39 per cent from 31 per cent.
NPAT rose to about $2.3m from $800,000 a year earlier, with operating cash flow stable at $1.5m.
Guerin notes the improvement reflects better margins and higher finance penetration, not increased volumes, and economic volatility remains a key theme in the financial year to date.
Outlook
Looking ahead, 2CC says it has identified opportunities to improve performance while remaining realistic about market conditions.
“We will better utilise our existing footprint through increased stock availability, faster preparation, and more consistent execution,” says Guerin.
“External factors, such as interest and exchange rates, may support customer financing and procurement, though both remain uncertain.
“We continue developing AI tools for vehicle selection, pricing, and operational decisions, and our new brand campaign aims to increase awareness and attract more customers directly.
“However, challenges persist, including price-sensitive customers, strong competition for stock in Japan, lower-priced new vehicles from Chinese manufacturers, and ongoing margin pressure from clean car standard charges.
“While encouraged by our progress, we recognise that trading conditions remain volatile.”